All Categories
Featured
Critical Analysis Into 2026 Debt Consolidation Trends
Eliminating Mounting Household Debt With 2026 Programs


Managing Excessive Consumer Debt in 2026
Table of Contents
Begin Today by Choosing Your Debt Quantity Below:( Needed) Your Approximated Debt Owed$ 0 $4,999$ 5,000 $7,499$ 7,500 $9,999$ 10,000 $14,999$ 15,000 $19,999$ 20,000 $29,999$ 30,000 $39,999$ 40,000 $49,999$ 50,000 $59,999$ 60,000 $69,999$ 70,000 $79,999$ 80,000 $89,999$ 90,000 $99,999$ 100,000+.
And more than a quarter of loan providers surveyed say 2.5 or more of their portfolio is presently in default. Top priority frequently identifies which financial institutions are paid and simply how much they recover, and there are increased difficulties over UCC concerns.
A Chapter 11 insolvency, also called a reorganization insolvency, is used to conserve and enhance the debtor's company. The debtor can also sell some possessions to settle particular financial obligations. This is different from a Chapter 7 individual insolvency, which generally concentrates on liquidating assets., a trustee takes control of the debtor's possessions.
Normally, at this phase, the debtor does not have an agreed-upon plan with monetary institutions to reorganize its debt. Comprehending the Chapter 11 personal bankruptcy treatment is essential for lenders, contract counterparties, and other parties in interest, as their rights and financial recoveries can be considerably affected at every phase of the case.
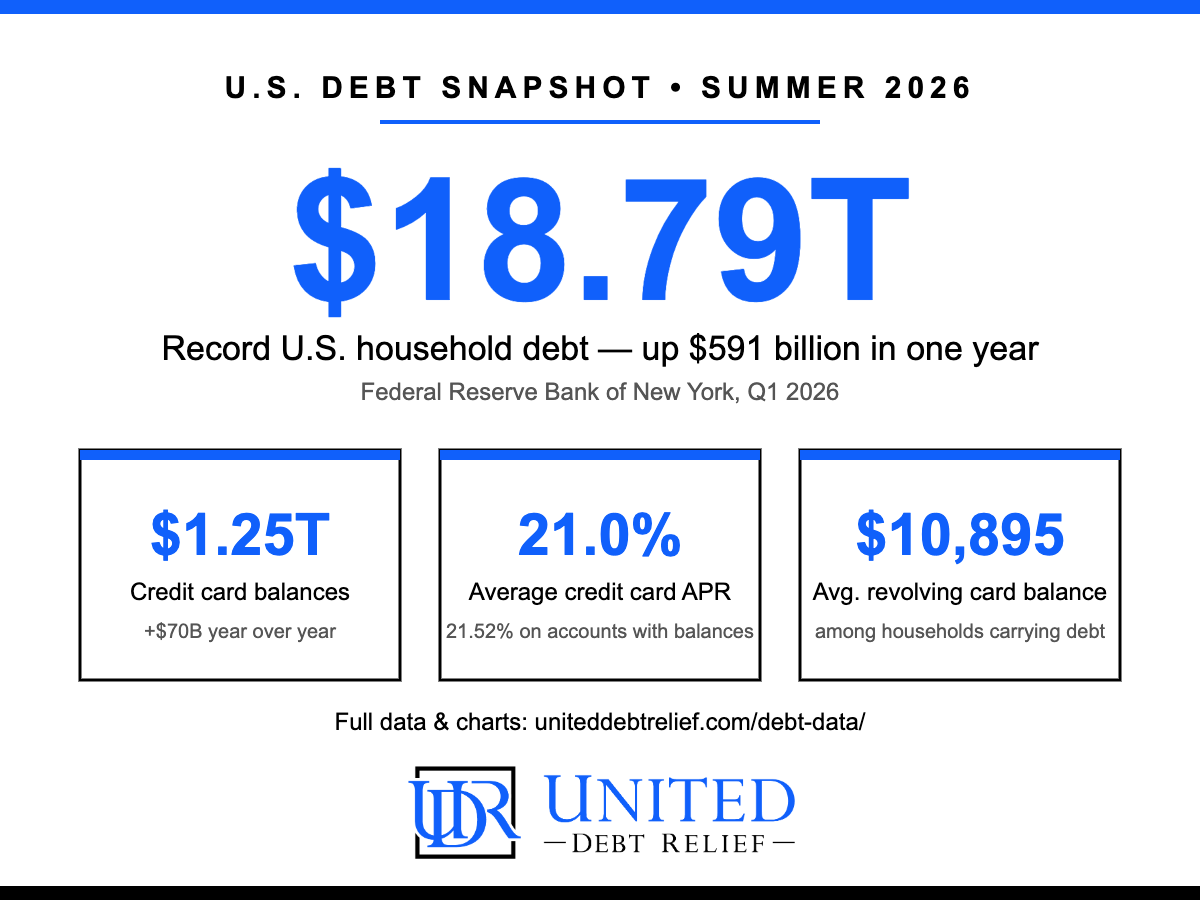
Should You Combine High-Interest Debt in 2026?
While operations may continue, the debtor goes through court oversight and need to get approval for great deals of actions that would otherwise be routine. APFSCDue to the reality that these motions can be comprehensive, debtors should thoroughly prepare ahead of time to guarantee they have the necessary permissions in location on the first day of the case.
Does Debt Settlement Still Make Sense Over Management Plans?The automated stay is a foundation of bankruptcy defense, developed to stop many collection efforts and provide the debtor breathing area to restructure. This includes getting in touch with the debtor by phone or mail, filing or continuing claims to gather financial obligations, garnishing salaries, or sending brand-new liens versus the debtor's residential or industrial property.
Hoodlum treatments are not stopped merely due to the fact that they include debt-related problems, and loans from most of occupational pension strategies should continue to be repaid. In addition, financial institutions might look for remedy for the automatic stay by sending a movement with the court to "lift" the stay, making it possible for particular collection actions to resume under court guidance.
As the case advances, the debtor is required to submit a disclosure statement in addition to a proposed strategy of reorganization that describes how it plans to reorganize its financial obligations and operations progressing. The disclosure declaration materials lenders and other celebrations in interest with comprehensive details about the debtor's company affairs, including its possessions, liabilities, and total financial condition.
The plan categorizes claims and defines how each class of financial institutions will be treated. Before the plan of reorganization is submitted, it is generally the subject of substantial settlements in between the debtor and its loan providers and need to stick to the requirements of the Personal bankruptcy Code. Both the disclosure statement and the strategy of reorganization must eventually be licensed by the personal bankruptcy court before the case can progress.
Should You Consolidate Your Debt in 2026?
Preferably, protected lending institutions would guarantee their legal claims are effectively taped before an individual bankruptcy case starts. Often the filing itself activates protected creditors to evaluate their credit files and ensure everything remains in order. By that time, their priority position is presently secured. Consider the following to mitigate UCC threat throughout Chapter 11.
After that, it ends and ends up being void. This indicates you wind up being an unsecured monetary institution and will need to wait behind others when residential or commercial properties are distributed. As a result, you may lose most or all of the homes connected to the loan or lease. When personal insolvency procedures begin, the debtor or its observing representative utilizes the addresses in UCC filings to send important alerts.
Even if you have a legitimate ensured claim, you may lose the opportunity to make essential arguments and claims in your favor. Keep in mind: When submitting a UCC-3, simply make one adjustment at a time. The court held that PMSI holders bear the responsibility of sending notification to the present protected celebration at the address noted in the most existing UCC filing, and that a previous protected celebration has no responsibility to forward notifications after a job.
Missing out on or misdirected notices can cost lenders make the most of, concern, and the possibility to secure their claims when it matters most.

Latest Posts

Critical Analysis Into 2026 Debt Consolidation Trends
Expert Analysis Into 2026 Credit Relief Trends
Eliminating Mounting Household Debt With 2026 Programs